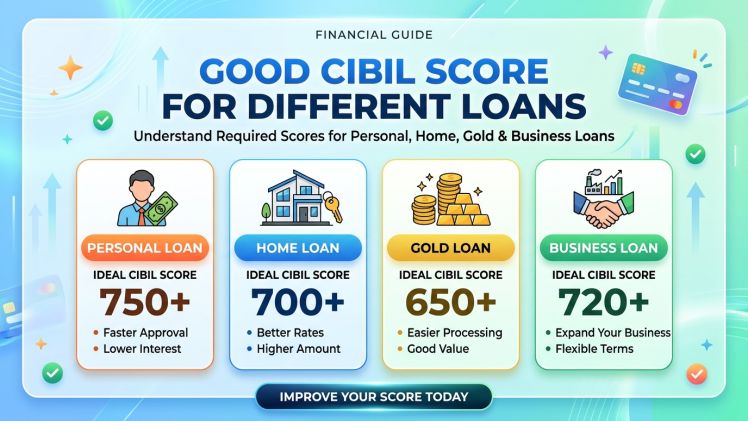
The CIBIL score is the first filter that determines the eligibility of your financial requests by summarising your entire credit history into one three-digit number. Even if having a score greater than 750 is always considered the best possible score, there is no standard score at all that ensures approval for any kind of financial tool.
The criteria set by lenders vary significantly based on whether you are applying for a secured loan or an unsecured loan and whether you are applying on your own or applying with a co-applicant.
How Are The Ranges Considered For A CIBIL Score?
In order to have insight into the evaluation process used by lenders, one needs to consider the following general bands for credit scores:
- 750-900 (Excellent): Gets good interest rates, no processing fee and immediate acceptance
- 700-749 (Good): Extremely negotiable and secure in almost all retail loans.
- 650-699 (Average): Good for secured loans, but very bad for unsecured ones.
- Less than 600 (Bad): Very high chances of loan denial and extortionate interest rates.
When It Comes To Personal Loans?
When it comes to personal loans, they ask for no collateral for approval, which means that you cannot mortgage anything, like property or a car, to get the money. Since all the responsibility lies with the lender in case you fail to repay the money, the lender becomes extremely careful while evaluating.
For an easy personal loan process, a CIBIL score above 750 is very essential, though some lenders do start offering loans starting from a CIBIL of 650, but a CIBIL above 750 brings lower interest for you as a borrower. The lender only considers your record of repaying loans on time and your employment stability to judge your financial behaviour.
If the score falls below 650, there are chances that the lender will ask for more documentation, deny loan offers, or increase the rates to cover their risks. Moreover, applying for many personal loans in a short span will affect your credit score greatly.
When Is It About Home Loans?
A mortgage or home loan carries a huge transaction value and repayment tenure that can continue anywhere from 20 to 30 years. Since the home loan is secured against the property asset, there is always a back-up plan for the lender, reducing the risks to a small extent.
The basic benchmark of a CIBIL score of at least 700 to 725 is required for a mortgage. Those with a CIBIL of 750 often get a much lower interest rate.
Since the home loan amount is high, even a small interest rate difference of 0.5% can help you save thousands of rupees over a period of 20 years. If your own credit score is low, then you can consider adding a co-applicant who has a perfect credit history.
What About Gold Loans?
A loan against gold is the biggest exception to the rulebook around CIBIL scores. The loan against gold is a fully secured loan in which the borrower provides the physical gold as collateral to the lender.
As the physical value of the gold reduces the risk of defaulting on the part of the lender to zero, the requirements for the CIBIL score become highly flexible. In fact, the CIBIL score requirement is not as fixed, and even those who have a poor credit score of less than 600 can qualify for the gold loan because it depends on the loan you are collateralising with the lender.
The lenders pay heed only to the LTV ratio; that is, based on the weight and purity of your gold, they determine how much money you should be given. Incidentally, an excellent way of improving your damaged credit score is taking the gold loan and repaying it timely.
If Someone Wants To Borrow For Business
Business purpose credit includes loans to expand the business, buy assets, or manage working capital. If you want to be under the eligibility of it, you would need to have a CIBIL of 720 to 750 or above, along with a good commercial CIBIL score for the business as well.
In the case of SMEs or sole proprietorships, banks take into consideration the personal CIBIL score of the promoter, as the two are financially connected.
Even though strong cash flows over several years and good earnings may make up for a bad personal CIBIL in some cases, you would still have to provide thorough documentation. Banks will then verify your taxes, balance sheets, and debt-to-equity ratio before lending any money for your business.
How Can You Maintain Your Desired Score?
To make sure that your financial opportunities stay totally open whenever needed, you need to try to maintain your score at 750 or above. To maintain this goal, you only need to follow some simple financial practices.
- First, set up automatic payments for your monthly EMIs and credit card payments to avoid any chance of missing the payment date.
- Second, keep your credit utilisation ratio under control and do not exceed 30%-40% of your total credit limit per month.
- Third, get your credit report regularly, once a quarter and address any administrative errors in it because any error has the possibility to leave a mark on your credit profile even for years down the line.
To Sum Up
A score of over 750 on your CIBIL report is your most valuable asset in terms of finance, as it will ensure quick approvals and the best interest rates. Although borrowing against assets such as gold is an option, it is essential to always pay back your debts timely. If you want to accurately view what segment you are in when it comes to your score, you can check it on Bajaj Finance App, since checking your CIBIL is considered a soft inquiry and does not impact your CIBIL score.